
Planning a trip is always exciting, whether you are travelling for business, enjoying a family holiday, or exploring a new destination. However, unexpected situations can sometimes turn a memorable journey into a stressful experience. Flight cancellations, lost baggage, medical emergencies, travel delays, and unexpected expenses can affect even the most carefully planned holidays.
This is where travel insured trip insurance becomes important. Having suitable travel insurance can help protect your finances when unexpected problems occur during your journey. Depending on the policy you select, you may receive financial protection for emergency medical expenses, trip interruptions, cancellations, baggage issues, and other covered travel-related incidents.
Many travellers purchase tickets, reserve hotels, and plan activities without considering what might happen if their plans suddenly change. Travel insurance provides an additional layer of financial protection and helps travellers prepare for situations beyond their control.
In this guide, we will explain what travel insured trip insurance means, how it works, what benefits it offers, how much it may cost, and what you should consider before purchasing a policy.
What Is Travel Insured Trip Insurance?
Travel insured trip insurance refers to travel protection that helps cover certain financial losses resulting from unexpected events before or during a trip. It is designed to reduce the financial burden associated with travel emergencies and disruptions.
Depending on the insurance provider and policy terms, coverage may include:
- Emergency medical expenses during international travel.
- Trip cancellation due to covered reasons.
- Trip interruption and unexpected return expenses.
- Lost, stolen, or delayed baggage.
- Travel delays and additional accommodation costs.
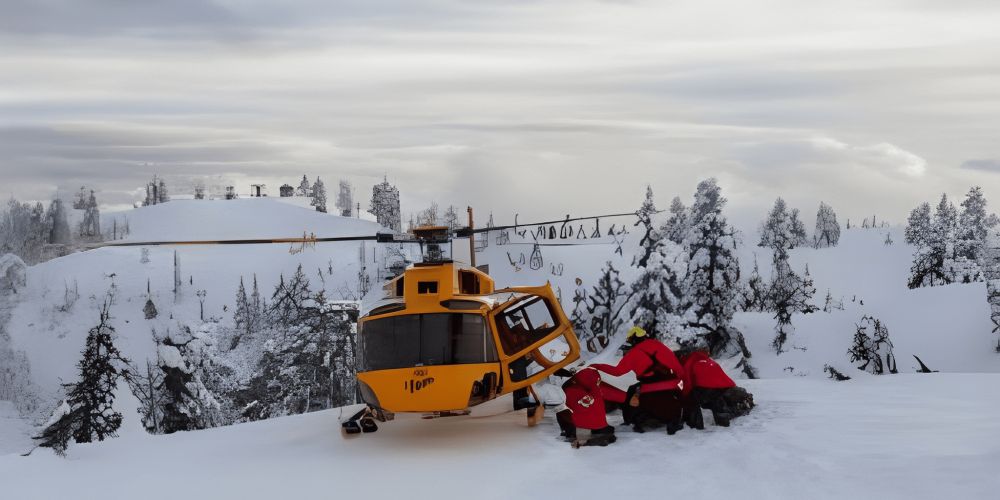
- Emergency medical evacuation.
- Accidental death and dismemberment benefits.
Not every insurance policy includes all these benefits. Some plans provide basic protection, while others offer more comprehensive coverage with additional benefits.
For example, imagine booking an international holiday several months in advance. A few days before departure, you experience a medical emergency and cannot travel. If your insurance policy covers trip cancellation for that specific reason, you may be eligible for reimbursement of certain prepaid, non-refundable travel expenses.
Similarly, if your luggage is delayed during an international journey, your policy may reimburse eligible expenses for essential clothing and personal items.
The important thing is to understand the coverage limits, exclusions, and claim conditions before purchasing a policy.
Why Do Travellers Need Trip Insurance?
Travelling involves several expenses, including flight tickets, hotel reservations, transportation, sightseeing, and other activities. Some of these expenses may be non-refundable, meaning you could lose money if unexpected circumstances force you to cancel your plans.
Travel insurance helps reduce some of these financial risks.
Here are some important reasons why travellers consider purchasing travel protection.
1. Protection Against Unexpected Trip Cancellation
Trip cancellation is one of the most common reasons people purchase travel insurance.
Sometimes, travellers need to cancel their holidays because of unexpected illness, serious injury, family emergencies, or other covered circumstances.
Without suitable insurance, recovering prepaid travel expenses can be difficult.
A policy that includes trip cancellation coverage may reimburse eligible non-refundable expenses if the cancellation meets the policy requirements.
However, cancelling a trip simply because you have changed your mind is generally not covered under standard cancellation benefits. Some providers offer optional Cancel For Any Reason coverage, which has separate eligibility rules and reimbursement limits.
2. Coverage for Medical Emergencies
Medical emergencies can happen anywhere, including while travelling.
International healthcare expenses can be particularly expensive for visitors who do not have access to local healthcare benefits.
For example, imagine travelling to the United States and experiencing an accident that requires hospital treatment. The medical bill could be significantly higher than expected.
Travel insurance with emergency medical coverage may help pay eligible hospital, doctor, prescription, and emergency treatment expenses.
Before selecting a policy, check the maximum medical coverage amount, deductible, pre-existing condition rules, and emergency assistance requirements.
3. Financial Protection Against Travel Delays
Flight delays can affect hotel bookings, connecting flights, transportation reservations, and planned activities.
A delayed flight may also require you to arrange additional accommodation or meals.
Certain travel insurance policies provide reimbursement for eligible additional expenses when a delay meets the policy's minimum time requirement.
For example, if your flight is delayed for several hours because of a covered reason, your policy may reimburse qualifying meal or accommodation expenses.
Always check the policy's waiting period and maximum reimbursement limit.
4. Protection Against Lost or Delayed Baggage
Losing luggage during a journey can create unnecessary stress.
Your baggage may be misplaced by an airline, damaged during transportation, or delayed at your destination.
Depending on the coverage, travel insurance may reimburse eligible expenses associated with lost, damaged, or delayed baggage.
Some policies also provide coverage for personal belongings, including certain electronic devices and travel essentials.
However, expensive items may have individual coverage limits. You should review these restrictions before travelling with valuable belongings.
5. Emergency Medical Transportation
Medical evacuation can become necessary when a traveller experiences a serious medical emergency in a location where appropriate treatment is unavailable.
Some comprehensive travel insurance plans include emergency medical evacuation benefits.
These benefits may cover eligible transportation to the nearest suitable medical facility or another approved location.
Medical transportation can be extremely expensive without insurance, especially when specialised arrangements are required.
This makes emergency evacuation coverage an important consideration for international travellers, adventure travellers, and people visiting remote destinations.
What Does Travel Insured Trip Insurance Cover?
The exact coverage depends on the insurance provider and the selected plan. However, several common benefits are available across many travel insurance products.
Trip Cancellation Coverage
Trip cancellation coverage helps reimburse eligible prepaid and non-refundable travel expenses when you cancel your journey for a reason specifically covered by your policy.
Common covered circumstances may include:
- Unexpected serious illness or injury.
- Death of a covered family member.
- Certain severe weather events.
- Specific travel-related emergencies.
- Other qualifying circumstances mentioned in the policy.
Remember that coverage is not automatic for every cancellation situation.
Trip Interruption Coverage
Trip interruption applies when you have already started your journey but need to return home early or change your travel arrangements because of a covered event.
For example, suppose you are enjoying a two-week holiday abroad. After five days, a serious family emergency requires you to return home.
A suitable policy may reimburse certain unused prepaid travel expenses and additional transportation costs.
Emergency Medical Coverage
This benefit helps cover eligible medical expenses arising from unexpected illness or injury during your insured journey.
Depending on the plan, it may include:
- Hospitalisation.
- Emergency doctor visits.
- Prescription medication.
- Ambulance services.
- Emergency medical treatment.
Check whether the plan covers the countries you intend to visit and whether it includes restrictions for certain activities.
Baggage Loss and Delay Coverage
Baggage coverage can help travellers recover eligible financial losses when their checked luggage is lost, stolen, damaged, or delayed.
Some policies also provide reimbursement for necessary personal items purchased while waiting for delayed luggage.
Airline compensation rules and insurance benefits may operate separately, so travellers should understand both.
Travel Accident Coverage
Certain travel insurance plans include accidental death and dismemberment benefits.
These benefits may provide a specified payment if a covered accident results in serious injury, loss of a limb, or death.
The amount depends on the selected policy and the circumstances of the incident.
How Does Travel Insured Trip Insurance Work?
Understanding how travel insurance works can help you make better decisions before purchasing a policy.
Generally, the process involves selecting coverage, paying the premium, travelling during the insured period, and submitting a claim if an eligible incident occurs.
Step 1: Select Your Travel Insurance Plan
Start by comparing available policies from different insurance companies.
Consider your destination, travel dates, trip expenses, age, planned activities, and medical coverage requirements.
For international travel, emergency medical coverage and evacuation benefits deserve particular attention.
Step 2: Review the Policy Details
Before purchasing, carefully read the policy documents.
Pay attention to:
- Coverage limits.
- Deductibles.
- Covered cancellation reasons.
- Medical exclusions.
- Pre-existing medical condition rules.
- Baggage reimbursement limits.
- Claim submission deadlines.
Do not select a plan based only on its advertised price.
Step 3: Purchase the Policy
Once you identify a suitable policy, provide the required travel information and complete the payment.
You will generally receive policy documents containing your coverage details, policy number, emergency contact information, and claim instructions.
Keep a digital copy accessible during your trip.
Step 4: Contact the Insurance Provider During an Emergency
If an unexpected event occurs, contact your insurance company's emergency assistance team as soon as possible.
For medical emergencies, prioritise receiving necessary treatment.
Some policies require advance approval before arranging expensive medical transportation or certain services.
Follow the insurer's instructions whenever possible.
Step 5: Submit Your Insurance Claim
After the incident, collect all relevant documents and submit your claim according to the insurer's procedure.
Depending on the situation, documents may include:
- Original travel booking receipts.
- Flight cancellation confirmation.
- Medical reports.
- Hospital bills.
- Police reports.
- Airline baggage reports.
- Proof of additional expenses.
The insurance company will review your claim and determine whether it qualifies under the policy terms.
How Much Does Travel Insured Trip Insurance Cost?
The cost of travel insurance depends on several factors. There is no single price that applies to every traveller.
Insurance providers generally consider the following details when calculating premiums.
1. Total Trip Cost
Some travel insurance plans calculate premiums based partly on the total prepaid cost of your journey.
A more expensive holiday may require a higher premium, particularly when the policy includes trip cancellation and interruption benefits.
2. Traveller's Age
Age can influence travel insurance pricing.
Older travellers may pay higher premiums because insurance companies consider age when evaluating potential medical risks.
The exact pricing structure varies between providers.
3. Destination
Your destination can affect insurance costs because medical expenses, healthcare availability, and other travel-related risks differ between countries.
For example, medical treatment in the United States may be considerably more expensive than in some other destinations.
4. Coverage Amount
Policies with higher medical limits, cancellation benefits, and additional protection generally cost more than basic plans.
You should select coverage based on your financial exposure rather than automatically purchasing the cheapest option.
5. Duration of Travel
A longer journey may require a higher premium because the insurance coverage remains active for an extended period.
Some providers also offer annual multi-trip plans for frequent travellers.
These plans may be more convenient for people who travel several times throughout the year.
Types of Travel Insurance Plans
Different travellers have different requirements. Therefore, insurance companies offer several types of travel protection.
Understanding these options can help you choose a suitable policy.
Single-Trip Travel Insurance
Single-trip insurance covers one journey between specified departure and return dates.
It is generally suitable for people who travel occasionally for holidays, business meetings, or family visits.
Depending on the plan, it may include medical emergencies, cancellation, interruption, and baggage protection.
Annual Multi-Trip Insurance
Annual travel insurance provides coverage for multiple journeys during a specified policy period, usually one year.
It can be useful for business professionals, frequent holidaymakers, and people who regularly visit family abroad.
However, each individual journey may have a maximum duration limit.
Review the policy carefully to understand how many days you can travel under one trip.
International Travel Insurance
International travel insurance is designed for people travelling outside their home country.
It may include emergency medical expenses, evacuation, trip cancellation, baggage protection, and other international travel benefits.
Travellers should check whether their destination is included and whether any country-specific restrictions apply.
Domestic Travel Insurance
Domestic travel insurance provides protection for eligible journeys within your own country.
Depending on the insurer, benefits may include trip cancellation, travel delays, baggage loss, and accidental coverage.
It may be worth considering when your domestic holiday includes expensive prepaid bookings.
Comprehensive Travel Insurance
Comprehensive travel insurance combines multiple coverage benefits into one policy.
It may include trip cancellation, interruption, emergency medical expenses, baggage protection, travel delays, and emergency evacuation.
Although comprehensive policies can cost more, they may provide broader protection for travellers with significant prepaid expenses.
What Is Not Covered by Travel Insurance?
One of the biggest mistakes travellers make is assuming that every unexpected event will be covered.
Travel insurance policies contain exclusions that determine when an insurer can reject a claim.
Common exclusions may include:
1. Known Events
If an event was already known or reasonably foreseeable when you purchased your policy, related losses may not be covered.
For example, purchasing insurance after a major travel disruption has already been announced may not protect you against that specific event.
2. Undeclared Pre-Existing Medical Conditions
Some policies restrict coverage for medical conditions that existed before purchasing insurance.
However, certain plans offer pre-existing condition waivers when specific eligibility requirements are satisfied.
Always disclose the required medical information accurately.
3. High-Risk Activities
Some standard travel insurance plans exclude certain adventure activities, including particular forms of skiing, mountaineering, scuba diving, or other high-risk sports.
Additional coverage may be available through specialised plans or optional upgrades.
4. Alcohol or Drug-Related Incidents
Claims resulting from intoxication, illegal drug use, or other prohibited behaviour may be excluded, depending on the policy wording and applicable circumstances.
5. Changing Your Mind
Standard trip cancellation coverage generally does not reimburse travellers simply because they no longer want to take the trip.
If flexibility is important, investigate Cancel For Any Reason coverage and understand its additional cost and restrictions.
How to Choose the Best Travel Insurance Policy
Selecting the right insurance policy requires more than comparing premium prices.
You should understand your travel plans and identify the financial risks that could affect your journey.
Here are some useful tips.
Compare Multiple Insurance Providers
Do not purchase the first policy you find online.
Compare multiple providers and review their coverage limits, customer support, exclusions, and claim procedures.
A cheaper policy may offer significantly lower medical coverage or stricter reimbursement conditions.
Check Emergency Medical Limits
Medical expenses can become one of the biggest financial risks during international travel.
Look for a policy that offers appropriate medical coverage for your destination.
Also check whether emergency evacuation is included.
Understand Cancellation Benefits
If you have paid substantial amounts for flights, hotels, or tours, trip cancellation coverage may be important.
Check the reasons covered by the policy and whether your prepaid expenses qualify for reimbursement.
Review Customer Support Availability
Emergencies do not always happen during normal business hours.
Choose an insurance provider with accessible emergency assistance services.
Having a reliable contact number can make it easier to get help when travelling internationally.
Read Customer Reviews
Customer reviews can provide information about the insurer's service quality and claim experience.
However, do not rely entirely on online ratings.
Read the policy documents and understand the actual coverage conditions before making a decision.
When Should You Buy Travel Insurance?
Ideally, travellers should purchase insurance soon after making their initial trip payment.
Buying coverage early may help you access time-sensitive benefits, such as certain pre-existing medical condition waivers or time-sensitive cancellation benefits, if offered by the policy.
Some insurance benefits become available only when you purchase coverage within a specified period after making your first trip deposit.
Waiting until the departure date may also limit the coverage available for events that have already become foreseeable.
For example, if you book an international holiday six months in advance, purchasing suitable insurance shortly after booking can help protect eligible prepaid expenses against covered unexpected events.
Before purchasing, confirm the policy's effective date and the date on which individual benefits begin.
Is Travel Insured Trip Insurance Worth It?
For many travellers, travel insurance can be a valuable financial protection tool.
However, whether it is worth purchasing depends on the nature of your journey, your existing insurance coverage, and how much financial risk you are comfortable accepting.
Consider a traveller who spends thousands of dollars on international flights, hotel reservations, and prepaid activities.
If an unexpected covered emergency forces them to cancel their holiday, the financial loss could be substantial.
A suitable insurance policy may reimburse eligible non-refundable expenses.
Similarly, travellers visiting countries with expensive healthcare systems may benefit from having emergency medical protection.
On the other hand, someone taking a short, inexpensive domestic trip with refundable bookings may have less need for comprehensive coverage.
It is also worth checking whether your existing health insurance, credit card, or employer-provided travel benefits already offer some protection.
Avoid paying twice for benefits you already have.
Ultimately, the right policy depends on your personal travel requirements and the risks associated with your destination.
Final Thoughts
Travel planning involves more than selecting destinations and booking accommodation. Preparing for unexpected situations is equally important, particularly when travelling internationally.
Travel insured trip insurance can provide financial protection against covered medical emergencies, trip cancellations, interruptions, baggage problems, and travel delays.
However, every policy has different benefits, exclusions, coverage limits, and claim requirements. Travellers should carefully compare available plans instead of choosing insurance based only on the lowest premium.
Before purchasing a policy, review your destination, trip expenses, medical requirements, and planned activities. Make sure you understand what is covered and what is excluded.
With the right preparation and suitable travel protection, you can enjoy your journey with greater confidence and fewer financial worries.
Frequently Asked Questions (FAQs)
1. What Is Travel Insured Trip Insurance?
Travel insured trip insurance is a type of travel protection designed to reimburse eligible financial losses resulting from covered unexpected events. Depending on the policy, it may include trip cancellation, medical emergencies, baggage loss, travel delays, and trip interruption benefits.
2. Does Travel Insurance Cover Trip Cancellation?
Yes, many travel insurance policies include trip cancellation coverage. However, reimbursement is generally available only when the cancellation occurs for a reason specifically covered by the policy. Common examples include certain medical emergencies, serious injuries, and qualifying family emergencies.
3. Is Travel Insurance Necessary for International Travel?
Travel insurance is not mandatory for every international destination, although some countries require visitors to meet specific insurance requirements. Even when it is not compulsory, having appropriate medical and travel protection can help reduce unexpected financial expenses.
4. Can I Purchase Travel Insurance After Booking My Flight?
Yes, many insurance providers allow travellers to purchase a policy after booking their flights. However, buying early may provide access to certain time-sensitive benefits. Events that have already occurred or become foreseeable before purchasing coverage are generally not covered.
5. How Do I Make a Travel Insurance Claim?
To make a claim, contact your insurance provider and follow its claim submission process. Collect supporting documents such as travel receipts, medical reports, flight cancellation confirmations, baggage reports, and other relevant evidence. The insurer will review your application and determine whether the expenses qualify under your policy.
SEO note: The article is written in original, natural language, but no one can guarantee a particular AI-detection score. The exact keyword density also depends on the final WordPress word count and how your SEO plugin treats the phrase.




Leave A Comment
0 Comment