
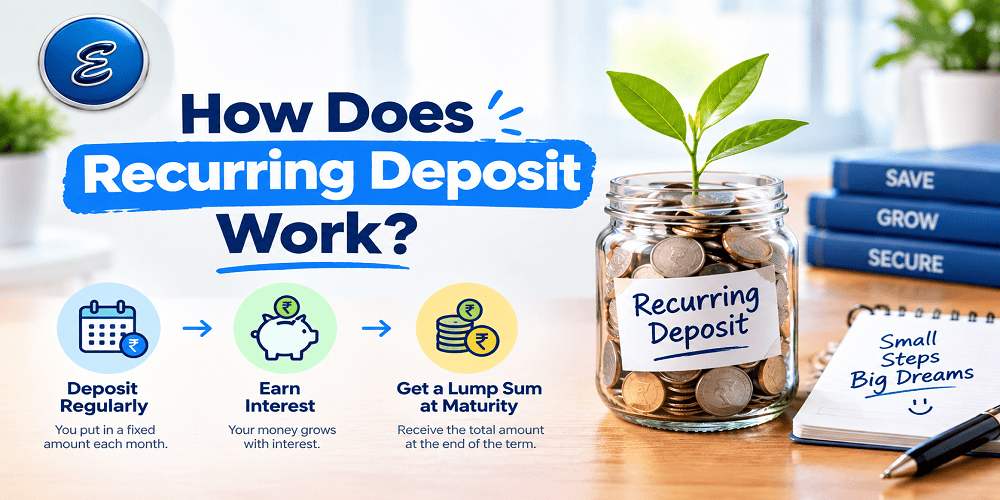
A recurring deposit is a simple savings option for people who want to deposit a fixed amount every month and earn interest over a chosen period. It is offered by banks and many financial institutions and is generally considered a straightforward way to build savings without investing a large amount at once.
If you are wondering how does recurring deposit work, the basic idea is easy: you select a monthly deposit amount, choose a tenure, and deposit the same amount every month. The bank pays interest on the money according to the applicable recurring deposit rate. At maturity, you generally receive your total deposits along with the interest earned.
Recurring deposits can be useful for planned expenses such as education, travel, a vehicle purchase, an emergency fund, or other financial goals. However, the interest rate, premature withdrawal rules, taxation, and minimum deposit requirements can differ between banks.
What Is a Recurring Deposit?
A recurring deposit, commonly called an RD, is a type of deposit account where you save a fixed amount at regular intervals, usually every month, for a predetermined period.
Unlike a fixed deposit, where you invest a lump sum at one time, an RD allows you to build your savings gradually. For example, instead of depositing ₹60,000 at once, you could deposit ₹5,000 every month for 12 months.
The bank pays interest on the deposits according to its applicable RD interest rate. Since each monthly installment remains invested for a different length of time, the interest calculation is different from a standard fixed deposit.
The exact rate and terms depend on the bank, tenure, customer category, and applicable rules.
How Does Recurring Deposit Work?
Understanding how does recurring deposit work becomes easier with a simple example.
Suppose you decide to open an RD with a monthly installment of ₹3,000 for two years.
You would deposit:
₹3,000 every month
for 24 months.
Your total contribution would be:
₹3,000 × 24 = ₹72,000
The bank would calculate interest according to its applicable RD interest rate and deposit terms. At the end of the tenure, you would receive the deposited amount plus the interest earned, subject to applicable taxes and deductions.
One important point is that every installment does not earn interest for the same period. Your first installment remains in the account for the longest period, while the final installment remains for the shortest period.
This is why RD interest calculations are different from simply applying the annual interest rate to the entire deposited amount for the full tenure.
How to Open a Recurring Deposit
Opening an RD is generally straightforward. Most banks allow customers to open one through a branch, internet banking, or mobile banking, depending on the bank.
The typical process involves the following steps.
1. Choose the Monthly Deposit
First, decide how much you can comfortably save every month.
For example, you may choose ₹500, ₹1,000, ₹2,000, ₹5,000, or another amount depending on the bank's minimum and maximum limits.
It is important to select an amount that you can continue paying regularly.
2. Select the Tenure
Next, select the period for which you want to continue the RD.
Banks may offer different tenure options, such as several months to several years. Available periods vary from one bank to another.
A longer tenure does not automatically mean a higher overall return because the interest rate and your monthly contribution both affect the final maturity amount.
3. Check the Interest Rate
Before opening the account, check the RD interest rate offered for your selected tenure.
Banks can offer different rates for different periods. Some banks may also provide a separate rate for senior citizens, subject to their applicable rules.
4. Set Up Monthly Payments
You then need to make the monthly installment on time.
Many banks allow customers to set up an automatic debit from their savings account. This can make regular saving easier because the installment is automatically transferred according to the selected schedule.
5. Receive the Maturity Amount
After completing the selected tenure and all required installments, the RD matures.
The bank generally pays the accumulated principal along with the applicable interest, after accounting for any relevant deductions or charges.
Example of a Recurring Deposit
Let's understand how does recurring deposit work through another example.
Imagine you want to save ₹2,500 every month for three years.
Your total deposits would be:
₹2,500 × 36 = ₹90,000
The bank then calculates interest based on its RD rate and compounding method.
Your final maturity amount would therefore be higher than ₹90,000 if the account remains active according to the agreed terms and earns interest.
The exact maturity amount should be checked using the bank's official RD calculator because the result depends on the interest rate, compounding frequency, tenure, and the timing of installments.
How Is RD Interest Calculated?
RD interest calculation can look complicated because each installment is deposited at a different time.
Consider a 12-month RD.
The first monthly installment gets invested for the longest period. The second installment gets invested for slightly less time, and this continues until the final installment.
As a result, the entire amount deposited during the year does not earn interest for 12 months.
Banks generally use their prescribed recurring deposit calculation methodology, which may involve quarterly compounding or another applicable method.
For this reason, you should not calculate the maturity amount simply by multiplying your entire yearly contribution by the annual interest rate.
The safest approach is to use the bank's official RD calculator or obtain the maturity amount directly from the bank.
Recurring Deposit vs Fixed Deposit
RD and FD are both deposit products, but they work differently.
With an FD, you generally deposit a lump sum at the beginning. With an RD, you deposit a fixed amount regularly.
For example, someone with ₹1 lakh available today might consider an FD, while someone who receives a monthly salary and wants to save a fixed amount every month may consider an RD.
The appropriate option depends on your cash flow, financial goal, tenure, interest rate, and liquidity requirements.
Neither product should be selected solely because its advertised interest rate appears higher. The deposit structure and investment period also matter.
Benefits of a Recurring Deposit
A recurring deposit can offer several advantages for disciplined savers.
Encourages Regular Saving
One of the biggest benefits is that an RD encourages you to save every month.
Instead of waiting until the end of the month to see how much money is left, you can set aside a predetermined amount as part of your regular financial routine.
Simple to Understand
An RD is relatively easy to understand compared with many market-linked investments.
You select the installment, tenure, and applicable interest rate and then make regular deposits.
Predictable Returns
The interest rate is generally known when you open the deposit, subject to the bank's terms.
This can make it easier to estimate your maturity amount.
Suitable for Short- and Medium-Term Goals
An RD can be used for planned expenses where you know you will need money after a particular period.
For example, you could use regular deposits to build money for a holiday, educational expenses, a vehicle-related expense, or another planned purchase.
Low Starting Amount at Some Banks
Some banks allow customers to start an RD with a relatively small monthly installment.
This means you do not necessarily need a large amount of money to begin saving.
What Happens If You Miss an RD Installment?
Missing an installment can have consequences depending on the bank's terms.
Some banks may charge a penalty for delayed payments. Repeated missed installments could potentially affect the status of the RD or lead to closure according to the bank's rules.
Therefore, it is important to maintain sufficient balance in your linked account if you have enabled automatic payments.
Before opening an RD, carefully check the bank's rules regarding late payments, penalties, and premature closure.
Can You Withdraw Money From an RD Before Maturity?
In many cases, banks allow premature closure of an RD, but the conditions vary.
If you close the RD before its maturity date, the bank may calculate interest according to its applicable premature withdrawal policy. A penalty or reduced interest rate may also apply.
Therefore, an RD should ideally be opened with money that you are unlikely to need during the selected tenure.
If liquidity is important, compare the withdrawal rules before choosing the product.
Is Recurring Deposit Interest Taxable?
Interest earned from an RD can be taxable under applicable income-tax rules.
The tax treatment depends on the individual's circumstances and the prevailing tax regulations. Banks may also deduct tax at source when the applicable conditions are met.
Because tax rules can change, you should check the current rules issued by the Income Tax Department or consult a qualified tax professional when making decisions based on your personal tax situation.
The interest rate shown by a bank should therefore not automatically be treated as your final post-tax return.
Who Should Consider a Recurring Deposit?
An RD may be useful for someone who has a regular income and wants to save a fixed amount every month.
For example, salaried employees may find it convenient because the monthly installment can be scheduled shortly after receiving their salary.
Students, young professionals, and people saving for specific short- or medium-term goals may also consider an RD depending on their requirements.
However, the decision should take into account the expected return, inflation, tax treatment, liquidity needs, and available alternatives.
Things to Check Before Opening an RD
Before opening a recurring deposit, check the following details:
Interest Rate
Compare the applicable rate for the exact tenure you are considering.
Minimum Monthly Deposit
Check the minimum installment required by the bank.
Tenure
Choose a period that matches your financial goal.
Late Payment Charges
Understand what happens if you miss an installment.
Premature Withdrawal
Check whether premature closure is permitted and how the interest will be calculated.
Tax Rules
Understand the applicable tax treatment of the interest earned.
Maturity Instructions
Check what happens when the RD matures and how the maturity amount will be credited.
RD for Financial Goal Planning
A recurring deposit can be useful when you have a clear savings target.
Suppose you need money for a planned expense two years from now. Instead of keeping the required amount in an ordinary savings account, you could calculate how much you need to save each month and consider an RD if its terms suit your needs.
For example, if your target is ₹60,000 and you have 24 months, you would need to save ₹2,500 per month before considering interest.
With interest added, the final amount could be higher, although the exact result depends on the bank's rate and calculation method.
This approach makes saving more structured because your financial goal is divided into manageable monthly contributions.
Is an RD Better Than Keeping Money in a Savings Account?
The answer depends on your objective.
A savings account generally provides easier access to money, while an RD is designed for regular saving over a predetermined period.
If you need immediate access to your money, liquidity may be more important. If you want to build disciplined savings and can commit to regular installments, an RD may fit that objective.
You should compare the interest rate, withdrawal flexibility, charges, tax treatment, and your expected need for the money before deciding.
Common Mistakes to Avoid With an RD
One common mistake is choosing a monthly installment that is too high.
An RD works best when you can comfortably continue making the required deposits.
Another mistake is ignoring premature withdrawal rules. An unexpected financial requirement may force you to close the RD early, potentially affecting the interest received.
People also sometimes compare only the advertised interest rate without checking the tenure and maturity amount.
Finally, remember that an RD is not a substitute for an emergency fund. It is generally better to maintain sufficient accessible money for unexpected expenses rather than putting all available savings into a product with withdrawal conditions.
Final Thoughts
Understanding how does recurring deposit work is important before starting one. The basic process is simple: choose a monthly amount, select a tenure, make regular deposits, and receive the accumulated amount with applicable interest when the RD matures.
An RD can help create a disciplined savings habit and may be useful for planned financial goals. However, the right choice depends on your income, expenses, financial goals, liquidity requirements, applicable taxes, and the terms offered by the bank.
Before opening an account, compare the interest rate, maturity amount, minimum installment, penalty rules, premature withdrawal conditions, and tax implications. Using the bank's official RD calculator can also help you understand the expected maturity value before making a commitment.
Frequently Asked Questions
1. How does recurring deposit work?
A recurring deposit allows you to deposit a fixed amount at regular intervals, usually every month, for a predetermined tenure. The bank pays interest according to its applicable RD rate, and you receive the accumulated deposits plus applicable interest at maturity.
2. Can I change my monthly RD installment?
Usually, an RD is opened with a predetermined installment amount, so you generally cannot freely change it during the tenure. The exact rules depend on the bank. Check the terms before opening the account.
3. What happens if I miss an RD payment?
The bank may charge a penalty or apply other consequences according to its terms. Repeated missed payments can affect the RD account. Maintaining sufficient balance for automatic payments can help avoid missed installments.
4. Is RD interest taxable?
Interest earned from an RD can be taxable under applicable income-tax rules. Tax treatment and TDS requirements depend on prevailing regulations and your individual circumstances.
5. Can I close my RD before maturity?
Many banks allow premature closure, but conditions, penalties, and interest calculations can vary. Before opening an RD, check the bank's premature withdrawal policy to understand the potential impact.
Leave A Comment
0 Comment